Commercial Real Estate Law in California: The Essential Guide to Acquisitions, Financing, Joint Ventures and Leasing
A commercial property can look excellent in a brochure and considerably less attractive in a purchase agreement. The rent roll may be optimistic, the zoning may limit redevelopment, and the financing may come with restrictions that complicate a future sale. Real estate has a way of making the fine print very expensive.
For investors and commercial property companies in California, success depends on understanding the legal framework behind the asset, not just its location or projected return. From acquisitions and financing to joint ventures, leasing, and eventual disposition, each stage presents decisions that can affect value, control, and profitability.
This guide explains the principal legal considerations for commercial real estate investors.
1. Start With the Investment Strategy
Before negotiating a purchase, determine what the property needs to deliver. A fully leased office building, a vacant retail center, and a development site may have similar asking prices but very different legal and financial risks.
An investor pursuing rental income will focus on tenant stability, lease terms, and operating expenses. A developer may be more concerned with zoning, entitlements, construction approvals, and the feasibility of a proposed change of use. A private investment firm may also need to consider how the asset fits within its fund documents, investor commitments, and exit timeline.
Define the Investment Thesis
Before committing capital, clarify:
· Income Expectations: Does the existing rent roll support projected returns, or do those returns depend on leasing vacant space or increasing rents?
· Development Potential: Are the proposed renovations or changes of use legally permissible, or will they require additional approvals?
· Capital Requirements: How much funding will be needed for acquisition, repairs, tenant improvements, reserves, and future development?
· Ownership Structure: Will the property be acquired directly, through a special-purpose entity, or as part of a joint venture?
· Exit Strategy: Will the investment be sold, refinanced, or held for long-term income, and could contractual restrictions affect that plan?
These decisions determine the scope of due diligence, the financing structure, and the protections that should be negotiated in the purchase agreement.
A sound investment strategy also distinguishes between what is already established and what remains a possibility. A permitted use is different from a proposed use awaiting approval. Contracted rental income is different from a forecast based on attracting future tenants. Investors should value each accordingly.
2. The Purchase Agreement: Establish the Rules Before Closing
A commercial purchase agreement is the foundation of the transaction. It establishes the purchase price, the parties' obligations, the diligence period, the conditions for closing, and the consequences of a failure to perform.
The details matter. A buyer who discovers a serious problem during due diligence needs sufficient time and contractual flexibility to decide what to do about it. Without appropriate protections, an attractive acquisition can become a dispute over deposits, deadlines, or alleged defaults.
Terms That Deserve Particular Attention
· Purchase Price and Deposit: Establish the payment terms, deposit arrangements, and circumstances in which the deposit may be refunded or retained.
· Due Diligence Period: Set realistic deadlines for inspections, title review, environmental assessments, lease analysis, and financing.
· Seller Documents: Specify the records the seller must deliver, including leases, operating statements, service contracts, permits, and available environmental reports.
· Representations and Warranties: Negotiate appropriate statements about ownership, authority to sell, litigation, leases, and other material matters.
· Closing Conditions: Identify the approvals, releases, documents, and other requirements that must be satisfied before closing.
· Default and Remedies: Define available remedies and termination rights if a party fails to perform.
An as-is provision deserves particular care. It may allocate significant property-condition risk to the buyer, but its effect depends on the agreement's language and applicable law. Buyers should not assume that a general as-is clause resolves every issue involving disclosures, fraud, or contractual obligations.
The agreement should also address what happens if due diligence reveals a material problem. Depending on the negotiated terms, the buyer may be able to request a price adjustment, require a cure, negotiate another protection, or terminate the transaction.
A commercial property acquisition attorney in Los Angeles can help buyers negotiate these provisions and assess whether the agreement gives them sufficient protection before they commit substantial capital.
3. Due Diligence: Investigate the Asset Behind the Asking Price
Due diligence tests whether the property's legal, physical, and financial condition supports the investment thesis. It should not be treated as a box-checking exercise completed after the important commercial decisions have already been made.
The California Lawyers Association identifies matters such as title, surveys, environmental assessments, building inspections, leases, and zoning as important elements of a commercial property transaction. The precise scope depends on the property, the buyer's objectives, and lender requirements.
Title, Surveys, and Recorded Restrictions
A title review helps establish the seller's ownership interest and identify recorded matters affecting the property. These may include mortgages, tax liens, easements, restrictive covenants, access rights, and other encumbrances.
A survey can reveal boundary discrepancies, encroachments, and the location of improvements relative to property lines. Buyers should also review title insurance coverage and its exceptions rather than assuming that insurance eliminates every ownership risk.
The key questions are whether the seller can convey the expected interest, which restrictions will remain after closing, and whether any identified issue interferes with the intended use.
Physical Condition and Environmental Risks
A building inspection should assess structural components, roofing, electrical systems, plumbing, heating and cooling equipment, and deferred maintenance. The findings should inform the capital expenditure budget, not simply sit in a report.
Environmental review is equally important for properties with potentially concerning historical uses, such as industrial operations, fuel storage, automotive facilities, or dry cleaning. A Phase I Environmental Site Assessment can identify recognized environmental conditions that warrant further investigation.
The U.S. Environmental Protection Agency explains that All Appropriate Inquiries is a process used to evaluate environmental conditions and assess potential liability under federal environmental law. Certain purchasers may qualify for liability protections, but those protections are conditional and require compliance with applicable requirements before and after acquisition. A Phase I assessment alone does not automatically eliminate environmental liability.
Financial and Operational Review
The financial records should be reconciled against the property's actual operations. Review rent rolls, operating statements, arrears, property tax records, insurance costs, service contracts, maintenance expenses, and planned capital expenditures.
A property reporting strong net operating income may still require significant near-term investment. Likewise, projected returns based on assumed rent increases may depend on lease provisions, market conditions, or approvals that have not been secured.
The objective is to determine whether the property can deliver the income, permitted use, and flexibility assumed in the investment model.
4. Zoning and Land Use: Verify What the Property Can Become
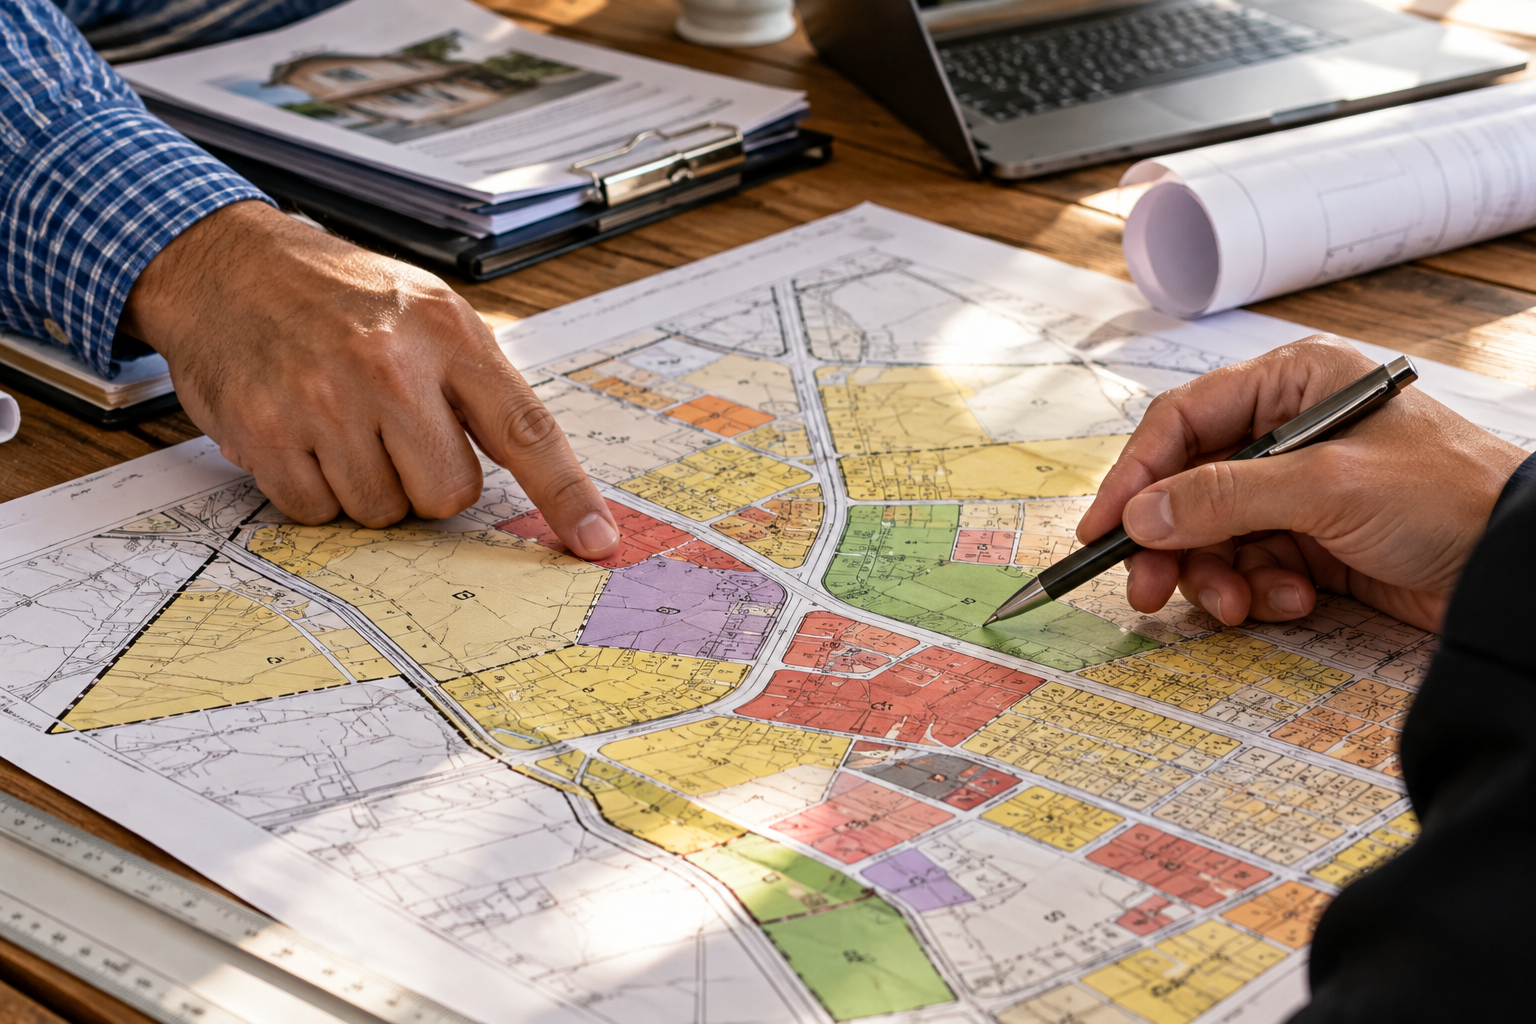
A building's physical layout does not establish that every proposed use is legally permitted. Zoning rules, land-use regulations, building approvals, and property-specific restrictions may limit how an asset can be occupied, modified, or redeveloped.
This matters particularly when the investment thesis depends on a change of use, expansion, additional density, or redevelopment.
Investigating Property-Specific Requirements
The City of Los Angeles provides the Zone Information and Map Access System (ZIMAS), which allows users to investigate zoning designations, planning applications, and certain permit records associated with a property.
ZIMAS is a useful starting point, but buyers should also review applicable ordinances, community plans, existing entitlements, building records, open code-enforcement matters, and approval requirements for the proposed project.
Beverly Hills has its own municipal zoning and planning requirements. Rules that apply to a property within the City of Los Angeles should not automatically be assumed to apply to a property in Beverly Hills or another California municipality.
What Buyers Should Confirm
· Permitted Uses: Whether the intended business or occupancy is allowed.
· Existing Improvements: Whether available records support the property's current configuration and use.
· Building and Occupancy Approvals: Whether the relevant permits and approvals are in place.
· Outstanding Violations: Whether unresolved safety, building, or code-enforcement matters exist.
· Future Development: Whether proposed construction or conversion requires further approvals and whether those approvals are realistically obtainable.
A property advertised as having redevelopment potential may still require discretionary approvals, additional studies, or significant investment before that potential can be realized. Investors should not pay for an assumed future use without investigating its legal feasibility.
5. Financing: Look Beyond the Interest Rate

The financing package can determine whether an acquisition is viable and how much flexibility the owner retains after closing. Commercial real estate financing may involve a promissory note, deed of trust, loan agreement, guarantees, assignments of rents, and other collateral documents.
Investors may use senior debt, sponsor equity, mezzanine financing, or other arrangements. Each structure affects leverage, repayment obligations, collateral, control, and the consequences of default.
Loan Terms That Can Change the Economics
· Interest and Fees: Consider the interest rate, origination fees, exit fees, and other financing costs.
· Repayment Structure: Review amortization, maturity, balloon payments, and anticipated refinancing needs.
· Collateral and Guarantees: Understand which assets secure the loan and whether guarantors may have personal exposure.
· Reserve Requirements: Determine whether funds must be maintained for taxes, insurance, repairs, or tenant improvements.
· Transfer Restrictions: Review conditions governing sales, ownership changes, additional debt, and transfers of interests in the borrower.
· Financial Covenants: Identify required financial ratios, reporting obligations, and other ongoing conditions.
A lower interest rate is not necessarily the better deal if it comes with restrictive covenants or a maturity date that does not align with the investment horizon.
Loan Covenants and Refinancing Risk
Loan covenants may govern leasing, property maintenance, insurance, financial performance, additional borrowing, and transfers of ownership. A breach can trigger consequences ranging from additional lender oversight to default remedies, depending on the documents and circumstances.
For example, an owner planning a major renovation or a substantial lease transaction should determine whether lender consent is required before making commitments.
Refinancing risk also deserves attention. If a loan matures before the property is stabilized or before major leases expire, the owner may need to refinance or sell under unfavorable conditions. Investors should stress-test the business plan against lower rental income, higher borrowing costs, and delays in executing the intended strategy.
6. Ownership Structures and Joint Ventures: Put Governance in Writing
Commercial property may be held directly or through a limited liability company, partnership, corporation, or other entity. The appropriate structure depends on ownership arrangements, financing requirements, tax advice, liability considerations, and the broader investment strategy.
A separate entity may help organize ownership and financing for an individual property, but it does not eliminate every liability or guarantee protection in every circumstance. Proper formation, governance, and ongoing maintenance remain important.
Joint Ventures Need Clear Decision-Making Rules
A real estate joint venture may pair a sponsor with operating expertise and investors providing capital. Their interests may align at acquisition but diverge when the property needs additional funding, a major repair, a refinancing, or an early sale.
The governing agreement should address:
· Management Authority: Who controls routine operations and which decisions require investor approval?
· Capital Contributions: How much each party must contribute, when additional capital can be requested, and what happens if a party fails to fund.
· Distributions: How operating cash flow and sale proceeds are allocated, including preferred returns or other agreed priorities.
· Major Decisions: Who approves refinancing, new debt, major capital expenditures, a sale, or a change in strategy?
· Transfers and Exit Rights: Can an investor transfer its interest, exercise a buyout right, or participate in a sale?
· Deadlock and Defaults: How are unresolved disagreements, funding shortfalls, and material breaches handled?
California LLC operating agreements can play a central role in defining the relationship between the company and its members. The agreement should reflect the actual commercial arrangement rather than rely on generic provisions that leave crucial decisions unanswered.
Investors should also consider whether the proposed investment interests constitute securities. Certain real estate investment arrangements can fall within securities laws, depending on their structure and circumstances. Applicable registration requirements or exemptions, disclosures, and other compliance obligations should be evaluated before interests are offered to investors.
When an ownership disagreement threatens operations, financing, or a sale, a partnership dispute lawyer in Los Angeles may help assess the governing documents and available options.
7. Commercial Leasing: Protect Income Without Sacrificing Flexibility
For an income-producing property, leases are central to valuation. They determine rental income, but they also shape maintenance obligations, occupancy rights, operating expenses, and the owner's ability to renovate or sell the asset.
Provisions Landlords and Tenants Should Examine
· Permitted Use: What activities may take place on the premises, and do they comply with applicable zoning and other restrictions?
· Rent and Operating Expenses: How are base rent, increases, common-area charges, taxes, insurance, and utilities calculated?
· Repairs and Maintenance: Who is responsible for structural elements, building systems, common areas, and tenant-specific improvements?
· Tenant Improvements: What approvals, permits, insurance, and construction standards apply?
· Assignment and Subletting: Can the tenant transfer the lease or sublet the premises, and what consent is required?
· Defaults and Remedies: What notices and cure periods apply, and what remedies are available under the agreement and applicable law?
· Renewal and Termination: How might options affect rental income, occupancy, redevelopment, or the timing of a sale?
Commercial leases should also be reviewed alongside the property's financing documents. Lenders may require tenant estoppel certificates or subordination, non-disturbance, and attornment agreements. These documents can affect the relationship between the lease, the lender's security interest, and the tenant's continued occupancy following certain enforcement actions.
A commercial lease attorney in Los Angeles can help landlords and tenants negotiate provisions that reflect their commercial objectives and reduce avoidable uncertainty.
Existing Leases Matter During an Acquisition
Buyers acquiring a tenanted property should review executed leases, amendments, side letters, rent records, security deposits, renewal options, and known disputes. A rent roll is a useful summary, not a substitute for the actual contracts.
Where appropriate, tenant estoppel certificates can help confirm key lease terms, payment status, and known defaults. If the investment depends on vacant possession or redevelopment, the buyer should verify the legal path to achieving it rather than assume tenants can simply be required to leave.
8. Property Taxes and Transaction Costs: Calculate the Real Cost
The purchase price is only one part of the acquisition cost. Investors should account for title and escrow charges, legal fees, inspections, financing expenses, insurance, immediate repairs, reserves, and applicable taxes.
California Property Tax Reassessment
A change in ownership can trigger reassessment under California property tax rules, subject to applicable exclusions. The California State Board of Equalization explains that a qualifying change in ownership generally leads to reassessment at current fair market value.
Investors should therefore avoid assuming the seller's existing property tax bill will remain unchanged after closing. The impact can be significant where the existing assessed value is substantially below the purchase price.
Entity-level transactions require particular care. A transfer of interests in an entity holding real estate may raise different questions from a direct property transfer, and applicable reassessment rules should be examined rather than assuming an entity transfer avoids tax consequences.
Los Angeles Transfer Taxes
The City of Los Angeles imposes a base real property transfer tax, and qualifying transactions may also be subject to Measure ULA.
According to the city's published guidance, for transactions closing after June 30, 2026, the ULA thresholds are $5.4 million and $10.9 million. Qualifying transfers above $5.4 million but below $10.9 million are subject to an additional 4% tax, while qualifying transfers of $10.9 million or more are subject to an additional 5.5% tax. The city's base transfer tax also applies.
These costs can materially affect seller proceeds and transaction negotiations. The applicable tax, calculation, exclusions, and contractual allocation should be verified for the particular transaction and closing date.
Transaction Costs at a Glance

The purpose of this analysis is to establish the property's total cost and likely ongoing obligations before the parties become committed to the transaction.
9. Managing the Property After Closing
Closing completes the acquisition, not the legal work. Owners must continue to comply with loan documents, lease obligations, insurance requirements, permits, entity governance requirements, and other applicable rules.
A practical post-closing process should include:
· Maintaining a calendar for loan payments, reporting obligations, insurance renewals, and required notices
· Tracking lease expirations, renewal options, rent escalations, and tenant improvement commitments
· Monitoring property taxes, assessments, and local compliance requirements
· Documenting major decisions, capital contributions, and approvals required under ownership agreements
· Reviewing proposed leases, refinancing, additional debt, and material renovations against existing contractual restrictions
Organized records also make future refinancing, investor reporting, and sale preparation more efficient. Missing approvals or incomplete lease records can create avoidable diligence questions when a new lender or buyer evaluates the asset.
10. Selling or Refinancing: Plan the Exit Before You Need It
An exit strategy should inform decisions made at acquisition. Investors who expect to sell in five years should understand how lease terms, loan maturity, capital improvements, and ownership agreements could affect the property's marketability.
A future sale may require review of leases, service contracts, warranties, title matters, environmental records, permits, and outstanding disputes. Sellers should identify which representations they can support and which liabilities require careful allocation in the purchase agreement.
Refinancing can present similar issues. A new lender may require updated appraisals, title and environmental reviews, financial statements, lease documents, and evidence of entity authority. Existing loan documents may restrict additional debt or require consent before refinancing.
In Los Angeles, transfer taxes and potential property tax consequences should be included in exit planning. Where the property is held through an entity, the legal and tax treatment of a sale of the real estate may differ from a transfer of entity interests.
The earlier these issues are considered, the more options investors may have to structure a transaction that aligns with their commercial objectives.
FAQs
What should I review before making an offer on a commercial property?
Start with the property's intended use, available operating information, preliminary title information, existing leases, known physical issues, and likely financing requirements. You may not have access to every document before making an offer, which is why the purchase agreement should provide appropriate diligence rights and a workable review period.
How long should commercial real estate due diligence take?
There is no universal timeline. The appropriate period depends on the property's complexity, the availability of records, the scope of inspections, lender requirements, and whether zoning or environmental concerns require further investigation. Buyers should negotiate a realistic period rather than assume it can be extended later.
What happens if due diligence uncovers a serious problem?
The available options depend on the purchase agreement and the nature of the issue. The buyer may be able to seek a price adjustment, require the seller to address the problem, negotiate another protection, or terminate the agreement under an applicable contingency. Buyers should understand these rights before their diligence period expires.
Can I change the use of a commercial property after purchasing it?
Not necessarily. The proposed use must comply with applicable zoning, land-use rules, building requirements, and other restrictions. A change of use may require permits or discretionary approvals, so investors should investigate feasibility before relying on redevelopment assumptions.
What should a real estate joint venture agreement say about additional capital?
It should specify when additional contributions may be required, how funding requests are approved, whether contributions are mandatory, and what happens if an investor does not contribute. The agreement may also address dilution, loans from other members, or other remedies, depending on the negotiated structure and applicable law.
Can my lender restrict a sale, refinancing, or major lease?
Yes. Loan documents may impose consent requirements or other restrictions on transfers, additional debt, major leases, or significant changes to the property. Owners should review these provisions before committing to a transaction that may require lender approval.
Will buying a commercial property increase my California property taxes?
A qualifying change in ownership can trigger reassessment at current fair market value, subject to applicable exclusions. Investors should estimate the potential effect before closing rather than assume the existing tax bill will continue unchanged.
What additional costs should I budget for when buying commercial real estate in Los Angeles?
In addition to the purchase price, budget for legal and escrow fees, title insurance, inspections, environmental assessments, financing fees, insurance, repairs, reserves, property tax adjustments, and applicable transfer taxes. Higher-value transactions within the City of Los Angeles should be evaluated for potential Measure ULA liability.
Should I hold each property in a separate LLC?
A separate entity may help organize ownership, financing, and risk allocation, but it is not automatically the right structure for every investment. The decision should account for lender requirements, tax advice, ownership arrangements, liability considerations, and the broader investment strategy.
When should I involve a real estate attorney?
Ideally, involve counsel before signing a binding purchase agreement. Early advice can help negotiate diligence rights, closing conditions, representations, and remedies before the parties become committed. Counsel can then help evaluate findings, review financing and ownership documents, and address outstanding legal issues through closing.
Make the Legal Structure Work for the Investment
Commercial real estate is not simply a matter of acquiring an asset and collecting rent. The purchase agreement defines the transaction, due diligence tests the asset, financing establishes operating constraints, ownership documents determine governance, and leases shape income and flexibility. Each decision can affect the next, and ultimately influence the property's value and exit options.
For investors and commercial property companies operating in Los Angeles, Beverly Hills, and Century City, careful legal planning can help identify risks before they become expensive problems. Local zoning, taxes, and transaction requirements also deserve property-specific review; California-wide principles do not eliminate municipal differences.
At Alex Nahai Law, we help businesses navigate transactions and legal issues that require commercial judgment as well as careful drafting. Whether you are evaluating an acquisition, negotiating financing, structuring a joint venture, or reviewing a commercial lease, we can help you assess the legal considerations and develop protections suited to your transaction.
Planning a commercial real estate transaction in California? Contact us to discuss your next steps.